New York Consumer Rights & Foreclosure Defense Representation by Application / (718) 957-8140 Call Now
Attorney Advertising
Case Study · Foreclosure Defense · Kings County

U.S. Bank wanted to winwithout a trial.The court said no.

3 holesIn the bank's proofEach one enough to deny it. No shortcut to a foreclosure.

Facing foreclosure? Petroff Amshen LLP is a New York consumer rights and foreclosure defense law firm. We find the defense in your file and take it to court.

Free case review. Confidential. Representation is by application.

The Result
What the court found
3 holes
The phone number, the 90-day notice and the meeting rule.
U.S. Bank's motion
Denied
Also denied: striking the answer and naming a referee.
Its meeting attempt
Too early
February 16, 2018, before any default it claimed.
Supreme Court, Kings County · Steven Amshen, Petroff Amshen LLP · 2026
Prior results do not guarantee a similar outcome. Every case turns on its own facts.
The Case

Summary judgment is how banks usually win foreclosures.
U.S. Bank didn't get it.

Quick AnswerIn a Decision and Order dated January 2, 2026, and entered January 15, 2026, Justice Menachem M. Mirocznik of the Supreme Court, Kings County, denied with prejudice a motion for summary judgment by U.S. Bank National Association, as trustee for a mortgage trust, in its foreclosure of a mortgage signed by our client on a Brooklyn property. The court found three separate holes in the bank's proof: the copy of its RPAPL 1306 state filing had the borrower's phone number blacked out, it offered no proof that the company that mailed the 90-day notice was authorized to send it, and its attempt to arrange a required in-person meeting came before any default. Its requests to strike our client's answer and for a referee were denied as well. Steven Amshen of Petroff Amshen LLP represented our client.

What the bank tried

U.S. Bank National Association, as trustee for a mortgage trust, started this foreclosure on April 17, 2023. It was foreclosing a mortgage signed by our client on a Brooklyn property. Our client's answer raised the defenses that mattered, including New York's 90-day notice rule and the bank's duty to report that notice to the state.

The bank first moved for summary judgment in November 2024. After we filed opposition papers, it withdrew that motion. Then it tried again. This time it asked the court to grant foreclosure without a trial, strike our client's answer and appoint a referee to compute the debt. Its proof came from two Assistant Secretaries of Nationstar Mortgage LLC, the company it said was its servicer and attorney in fact.

In our experience, summary judgment is how banks usually win foreclosure cases. If this motion had been granted, the case would have moved straight toward a judgment of foreclosure. It wasn't.

How we beat it

Justice Menachem M. Mirocznik found three separate problems with the bank's case, and each one was enough to deny the motion.

The phone number. RPAPL 1306 requires a lender to file information about its 90-day notice with the New York Department of Financial Services, including the borrower's last known phone number. On the copy of the filing before the court, the space for the phone number was blacked out. The court held that this was "not a mere technical defect or irregularity" and that it undermined the statute's purpose of directing help to borrowers in need. As the court put it about New York's required foreclosure notices, "All three require strict compliance. All three require a phone number."

The 90-day notice. RPAPL 1304 requires the lender, assignee or loan servicer to mail the borrower a warning at least 90 days before suing. The bank's papers said the notices were sent by a different company, Rushmore Loan Management Services LLC. But the bank offered no proof that Rushmore was authorized to send them, so it couldn't show strict compliance.

The in-person meeting. A federal rule, 24 CFR 203.604, requires the lender to meet with the borrower, or make a reasonable effort to arrange a meeting, before three full monthly payments go unpaid. The bank pointed to an attempt on February 16, 2018. Its own complaint put the default at April 1, 2018. The court agreed with us that an attempt made before any default does nothing for the rule's purpose. In the court's words, "It defied logic that loss mitigation can occur when a defendant is not in default and no loss occurred." The court also found that the bank's proof of that letter was "conclusory," that the letter appeared to come from Wells Fargo with no proof Wells Fargo was the servicer at the time, and that the bank's own records showed any earlier default had been cured.

What the court ordered

The Decision and Order is dated January 2, 2026, and was entered January 15, 2026.

  • The bank's motion for summary judgment, to strike the answer and for a referee was denied with prejudice.
  • Because of those three failures, the court held the bank never made the initial showing it needed, so the motion failed on the bank's own papers.
  • The case now proceeds to trial.
Three holes in the bank's proof. Any one was enough.
Timeline

From the 2023 lawsuit
to the January 2026 ruling.

The state filing
The phone number, blacked out.
The 90-day notice
No proof the sender was authorized.
The meeting attempt
Before any default.

From the court's Decision and Order dated January 2, 2026. On the meeting rule, the court held the motion "must be denied for this reason as well."

  1. Apr 2023
    U.S. Bank sues to foreclose.
  2. Nov 2024
    Its first motion, withdrawn after we opposed it.
  3. Jan 2026
    The court denies U.S. Bank's motion.
The Legal Record · Summary Judgment

February 16, 2018.
Before any default.

The record, in order: what the law requires, what U.S. Bank offered, and what the court held on each argument.

The 90-day notice · RPAPL 1304
90 days
Before suing, from the lender, assignee or loan servicer.
The meeting rule · 24 CFR 203.604
3 monthly payments
The meeting, or a reasonable effort to arrange one, comes before they go unpaid.
The argumentU.S. Bank saidThe Court held
01
The phone number is required.RPAPL 1306 · state filing
U.S. Bank saidIt complied with RPAPL 1306.
The Court heldRejected
The space for the borrower's phone number was blacked out, which is "not a mere technical defect or irregularity."
02
The sender must be authorized.RPAPL 1304 · 90-day notice
U.S. Bank saidIt sent the required notices.
The Court heldRejected
The notices were sent by Rushmore Loan Management Services LLC, and "no proof is proffered that Rushmore was authorized to send the subject notices."
03
The meeting attempt must come in time.24 CFR 203.604 · in-person meeting
U.S. Bank saidIt tried to arrange a meeting on February 16, 2018.
The Court heldRejected
Its complaint put the default at April 1, 2018. "It defied logic that loss mitigation can occur when a defendant is not in default and no loss occurred."
04
The letter has to be proven.Proof of mailing
U.S. Bank saidIts officer said the meeting letter went by certified and first-class mail.
The Court heldRejected
The claim was "conclusory," and the letter appeared to come from Wells Fargo, with no proof Wells Fargo was the servicer at the time.
Blacked out, unproven, too early.Motion denied.
Facing a foreclosure like this one?
A licensed New York attorney reviews every application. Free and confidential.
Apply for Your Case Review
Legal Analysis · Plain English

What the Court decided,
and why it matters.

1. The bank has to prove its own case

When the borrower's answer raises New York's notice rules, the bank has to prove, as part of its own case, that it followed them strictly. Here it could not, so the motion "must be denied without regard to the sufficiency of the opposition papers."

2. A blacked-out phone number is not a technicality

RPAPL 1306 requires the lender's state filing to include the borrower's last known phone number. The court explained why it matters: the information is used to "direct appropriate services to borrowers in need," and leaving it out undermines that purpose. New York holds its other notice rules to the same standard. In the court's words, "All three require strict compliance. All three require a phone number."

3. The right company has to send the notice

RPAPL 1304 names who must give the 90-day notice: the lender, assignee or loan servicer. When another company sends it, the bank has to prove that company was authorized. Here it offered no such proof, so it could not show strict compliance.

4. A meeting attempt before any default does not count

The federal meeting rule is about loss mitigation: working with the borrower once payments go unpaid. An attempt made before the borrower is in default, the court held, does not accomplish that purpose. And the bank still has to prove the letter was actually sent.

What this means if you're facing foreclosure

It's easy to think of these notice rules as paperwork. New York courts treat them as conditions the bank has to meet before it can foreclose at all. Here the bank couldn't show who was authorized to mail the warning letter. The copy of its state filing had the phone number blacked out, and its attempt at a meeting came before there was anything to talk about.

Those defenses only help if someone raises them and holds the bank to its proof. That's what we do. If you've been served with foreclosure papers, call us before you answer, or as soon as you can after.

Attorney on the Case

The attorney
behind the win.
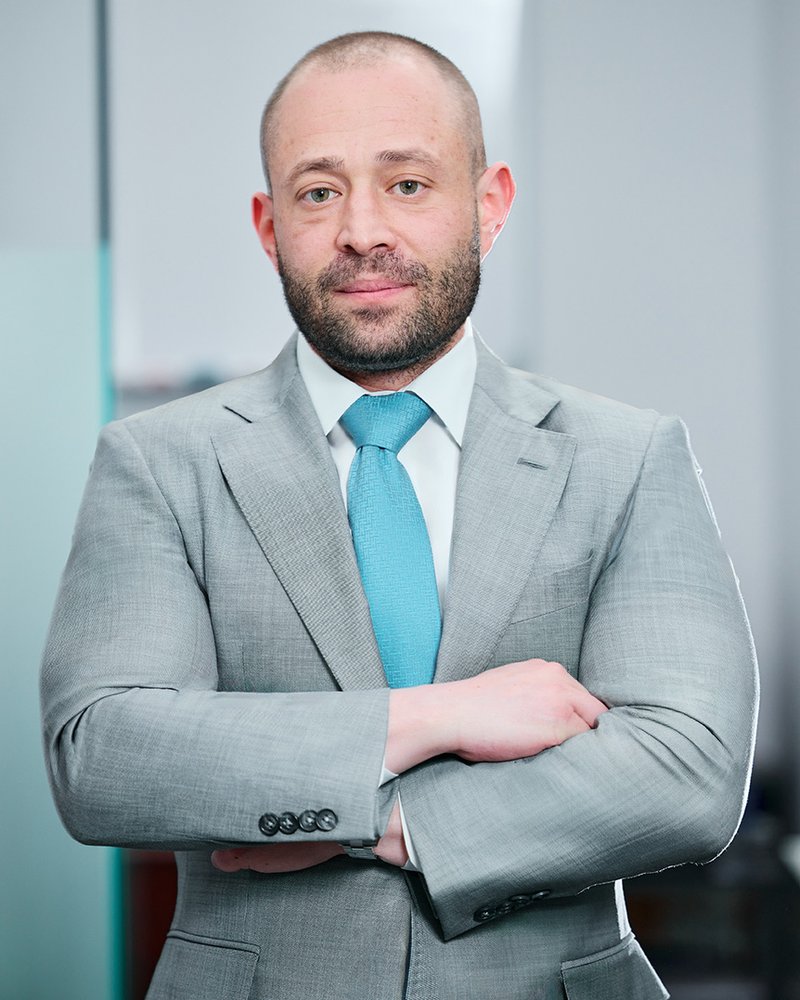
Steven Amshen, Petroff Amshen LLP
Partner

Steven Amshen of Petroff Amshen LLP represented our client in the Supreme Court, Kings County.

Profile
Questions

Questions people search
about summary judgment in foreclosure.

What is summary judgment in a foreclosure?
It is a ruling without a trial. The bank asks the judge to decide the case on the papers alone. The court called it a "drastic remedy," and the bank has to prove its case with admissible evidence.
Does a blacked-out phone number on the state filing matter?
It did here. RPAPL 1306 requires the lender to file information about its 90-day notice with the New York Department of Financial Services, including the borrower's last known phone number. On the copy before the court, that space was blacked out, and the court held it was "not a mere technical defect or irregularity." Every case turns on its own facts. Prior results do not guarantee a similar outcome.
Who can send the 90-day notice?
RPAPL 1304 says the lender, assignee or loan servicer must give it. Here the bank's papers said a different company, Rushmore Loan Management Services LLC, sent the notices, and the bank offered no proof Rushmore was authorized to send them.
What is the federal meeting rule?
For the loans it covers, a federal rule, 24 CFR 203.604, requires the lender to meet with the borrower, or make a reasonable effort to arrange a meeting, before three full monthly payments go unpaid. Here the bank pointed to an attempt on February 16, 2018, and its own complaint put the default at April 1, 2018. The court agreed with us that an attempt made before any default does not serve the rule's purpose.
What should I do if I have been served with foreclosure papers?
Call a lawyer before you answer, or as soon as you can after. Defenses like the 90-day notice and the state filing only help if someone raises them and holds the bank to its proof. Here they were in our client's answer.
Does Petroff Amshen represent clients outside New York?
No. Petroff Amshen represents clients in New York only.
Glossary: the terms in plain English
Summary judgment
A ruling without a trial, when the papers show one side is entitled to win.
Trustee
Here, the bank suing on behalf of a trust that holds mortgage loans.
Loan servicer
The company that manages a mortgage loan.
Attorney in fact
An agent authorized by a power of attorney to act for someone else.
90-day notice
The warning letter a New York lender must mail a borrower before it can sue to foreclose (RPAPL 1304).
State filing
The lender's report of that notice to the New York Department of Financial Services (RPAPL 1306).
Meeting rule
A federal rule, 24 CFR 203.604, that requires a meeting with the borrower, or a reasonable effort to arrange one, before three full monthly payments go unpaid.
Strict compliance
Doing exactly what the statute requires. Close is not enough.
Referee
A person the court appoints to compute what the lender says is owed.
Petroff Amshen Reviews

What clients
have said.

★★★★★

I could not recommend a better group than Petroff Amshen. If you find yourself in a situation that requires the assistance of attorneys, this is the firm.

Eli Miller / Google
Prior results do not guarantee a similar outcome.
★★★★★

After years of battling in court, thousands of dollars in legal fees, and quite a few subpar attorneys, we found Petroff and Amshen, who delivered winning results. They're incredibly easy to talk to, making the whole legal process feel less intimidating.

Charlene J. / Google
Prior results do not guarantee a similar outcome.
★★★★★

An effective firm with a minimum of fuss. When you need attorneys who actually do the work, you need these guys on your side.

Joseph Petruzzo / Google
Prior results do not guarantee a similar outcome.
Apply for Your Case Review

Tell the firm
what happened.

Petroff Amshen does not take every case. Submit the application and a licensed New York attorney will review the matter directly. The case review is free and confidential.
  • 01Submissions are confidential.
  • 02Reviewed by a licensed New York attorney, not a call center.
  • 03Most applications are reviewed within one business day.
  • 04If the matter fits the practice, the firm reaches out to schedule a consultation. If not, the firm says so.
  • 05Fee structure is discussed at the consultation.
Steven Amshen, Petroff Amshen LLP
Partner, counsel on this case
If you would rather call
(718) 957-8140
Application for Case Review

Submitting this form does not create an attorney-client relationship. Petroff Amshen LLP does not sell, share, or disclose this information to any third party. All submissions are confidential and reviewed by a licensed New York attorney.