Attorneys on the Case
The attorneys
behind the win.
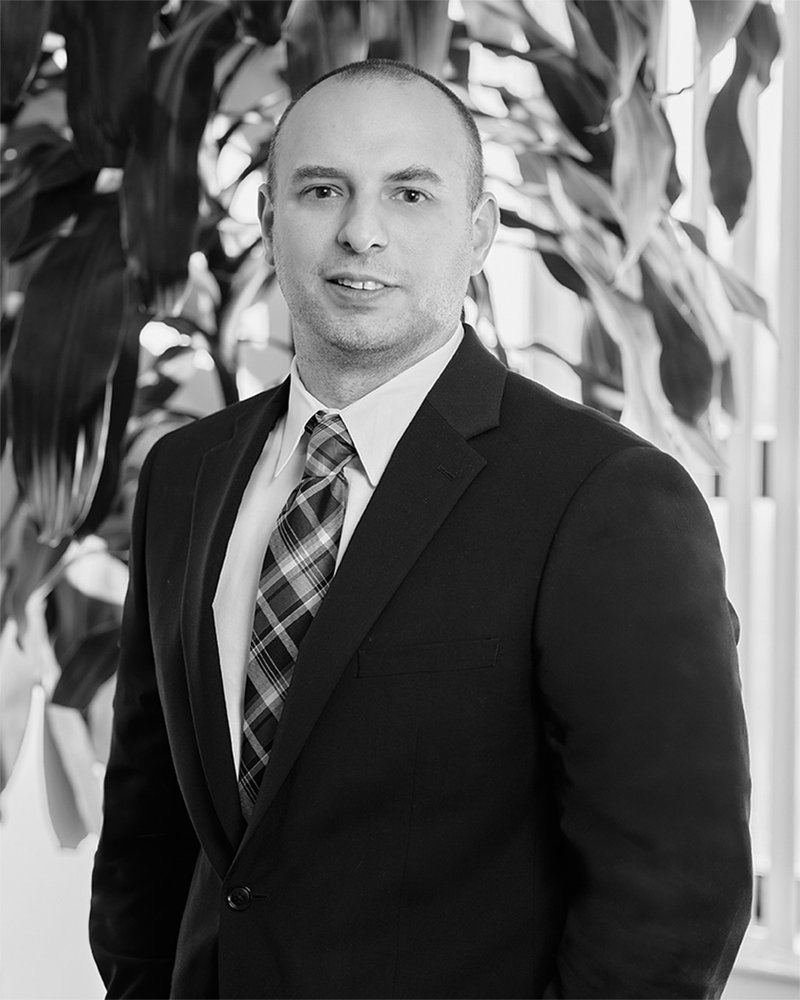
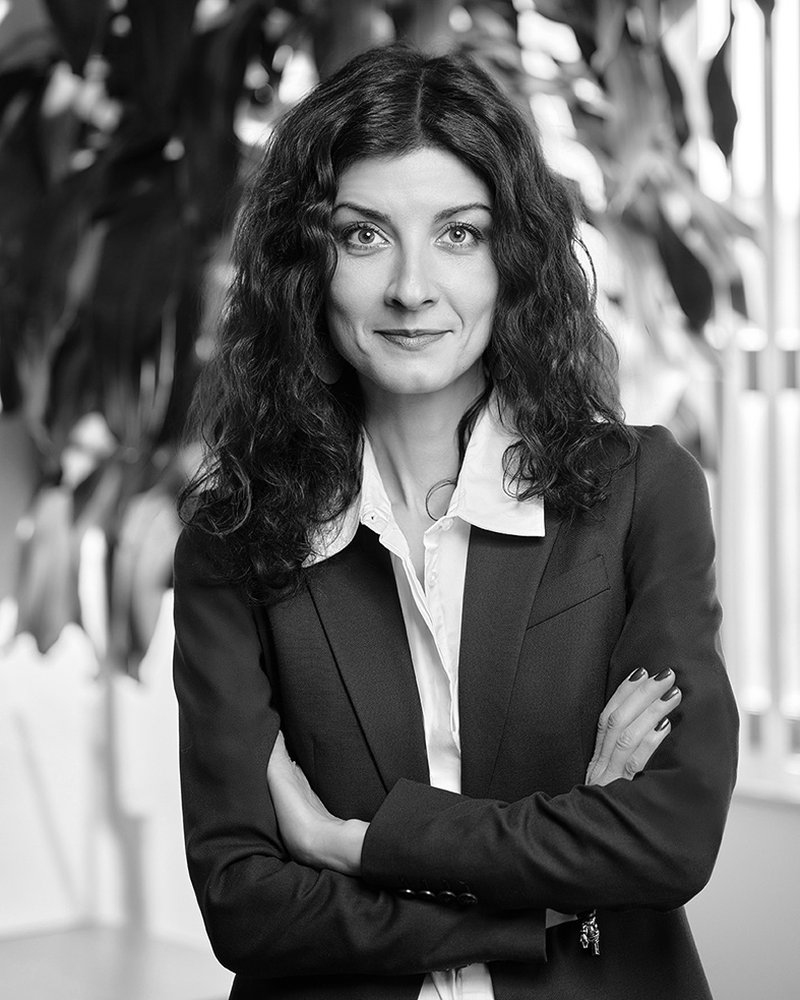
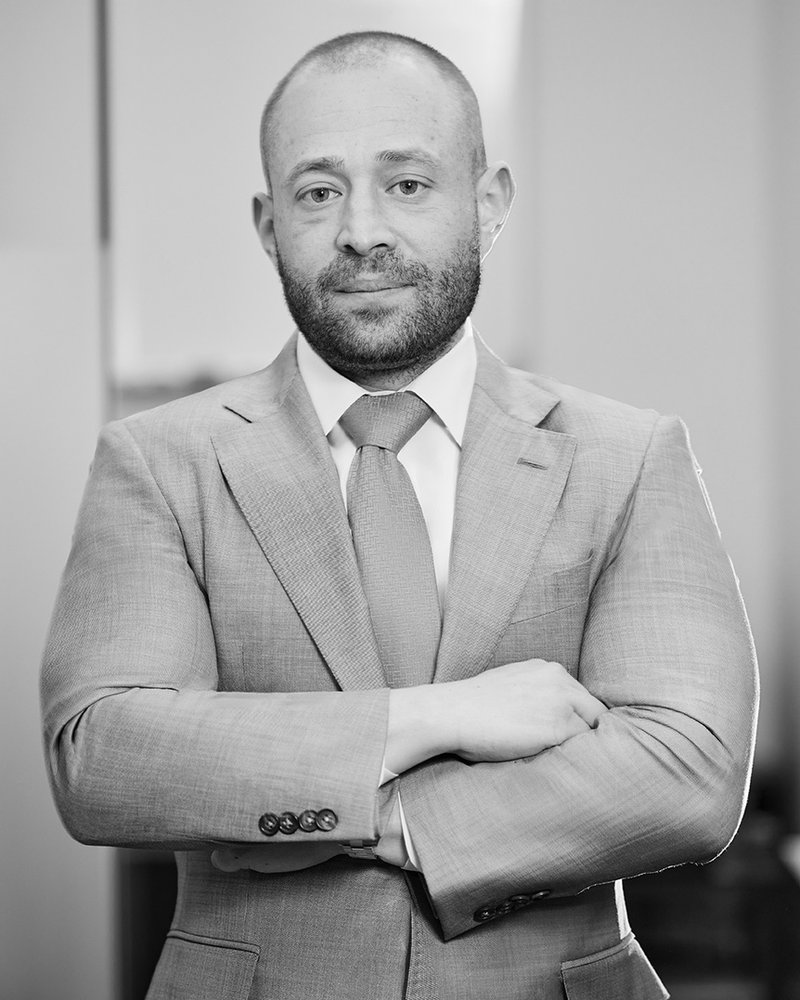
James Tierney, Maria Garber and Steven Amshen of Petroff Amshen LLP represented our client in the Appellate Division, Second Department.
Facing foreclosure? Petroff Amshen LLP is a New York consumer rights and foreclosure defense law firm. We find the defense in your file and take it to court.
Free case review. Confidential. Representation is by application.
Quick AnswerOn February 4, 2026, the Appellate Division, Second Department unanimously affirmed an order of the Supreme Court, Kings County that dismissed as time-barred a 2022 foreclosure brought by MTGLQ Investors, L.P., the company that took over the mortgage, against Petroff Amshen's client and granted her counterclaim under RPAPL 1501(4) to cancel and discharge of record the $397,765 mortgage on her Brooklyn property. The six-year statute of limitations began to run on September 9, 2010, when CitiMortgage sued and called the whole loan due, and under the 2022 Foreclosure Abuse Prevention Act the later discontinuances "did not serve to revive or reset the statute of limitations."
In New York a lender has six years to foreclose once it calls the whole loan due, and filing a foreclosure complaint that demands the full balance starts that clock. When the six years run out, the owner can ask the court to cancel the mortgage and clear it from the property records.
Under the Foreclosure Abuse Prevention Act, which took effect December 30, 2022, a lender that voluntarily drops its own foreclosure case does not get a fresh six years. That rule decided this case.
On April 27, 2007, our client signed a $397,765 note to CitiMortgage, Inc., secured by a mortgage on residential property in Brooklyn. On September 9, 2010, CitiMortgage sued to foreclose and elected in its complaint to call the entire balance due. It discontinued that case on February 23, 2011.
CitiMortgage assigned the mortgage to Nationstar Mortgage, LLC in April 2012. Nationstar filed a second foreclosure on December 4, 2013. In 2019 it asked to discontinue, and the court let it. Neither case reached a judgment.
On October 5, 2022, MTGLQ, saying it held the note, filed a third foreclosure, more than twelve years after CitiMortgage called the loan due. Our client answered that the case came too late and counterclaimed to cancel the mortgage.
Our client moved for summary judgment dismissing the case and on her counterclaim. MTGLQ's answer was to attack the 2022 law itself. It said the law did not apply retroactively to its loan, and that applying it would violate its due process rights and the Takings and Contracts Clauses of the United States Constitution.
On November 27, 2023, the Supreme Court, Kings County granted the motion. It dismissed the complaint against our client and, in effect, granted her counterclaim to cancel and discharge the mortgage of record. MTGLQ appealed.
Once a mortgage debt is accelerated, the entire amount is due and the Statute of Limitations begins to run on the entire debt.Appellate Division, Second Department, February 4, 2026
Our client had shown the clock started September 9, 2010 and that MTGLQ sued more than six years later. To stop summary judgment, MTGLQ needed to raise a real factual dispute, and the Appellate Division held it had not. The 2011 and 2019 discontinuances "did not serve to revive or reset the statute of limitations." MTGLQ's constitutional arguments were "without merit." All four justices agreed, and the order was affirmed with costs.
Both bars start on September 9, 2010, the day CitiMortgage sued and called the loan due.
The record, in order: what the law gives a lender, when MTGLQ filed, and what the courts held on each argument.
Under CPLR 213(4) a lender has six years to foreclose. Once the debt is accelerated, the six years run on the entire balance, and filing a foreclosure that elects to call the whole amount due is an acceleration. CitiMortgage's September 9, 2010 complaint did exactly that.
CitiMortgage discontinued its case in 2011, and Nationstar discontinued its case in 2019. CPLR 3217(e) and 203(h), both added by the Foreclosure Abuse Prevention Act, say a voluntary discontinuance does not revive or reset the limitations period. The Appellate Division applied them here.
MTGLQ filed its case in October 2022, before the law took effect. It argued the law did not apply retroactively, and that applying it would violate the United States Constitution. The Appellate Division held those arguments were without merit.
RPAPL 1501(4) lets a person with an interest in the property ask the court to cancel and discharge a mortgage once the time to foreclose has expired. Our client brought that claim as a counterclaim, and the order granting it was affirmed.
If a lender first demanded your full balance more than six years ago, the foreclosure you are facing now may be too late. Dropping an earlier case does not buy the lender more time.
The loan's full history matters. Here the date that decided everything was a complaint filed in 2010, twelve years before the case that was dismissed. Old court files and assignment records are where a defense like this is found.
Winning the case was only part of it. The Brooklyn court also granted the claim to cancel the mortgage of record, so it can be cleared from the property's title records. Ask about that claim from the start.
James Tierney, Maria Garber and Steven Amshen of Petroff Amshen LLP represented our client in the Appellate Division, Second Department.
I could not recommend a better group than Petroff Amshen. If you find yourself in a situation that requires the assistance of attorneys, this is the firm.
After years of battling in court, thousands of dollars in legal fees, and quite a few subpar attorneys, we found Petroff and Amshen, who delivered winning results. They're incredibly easy to talk to, making the whole legal process feel less intimidating.
An effective firm with a minimum of fuss. When you need attorneys who actually do the work, you need these guys on your side.
Petroff Amshen does not take every case. Submit the application and a licensed New York attorney will review the matter directly. The case review is free and confidential.